Evaluative Capability
The Missing Infrastructure of Development Finance
Dentons published research this month covering nine African markets, from Mauritius to the Democratic Republic of Congo, and the finding was blunt. International capital now increasingly moves according to environmental, social and governance standards that most domestic regulatory frameworks on the African continent have not caught up with (Muriithi, 2026). Banks and insurers seeking international funding find themselves answering to two systems at once: a set of external ESG expectations written elsewhere, and a domestic rulebook that in many jurisdictions has yet to mention sustainability at all.
The story is accurate, and it is also too small. ESG functions here as the visible edge of a much wider condition, one that runs through the entire architecture of development finance. Governments are required to satisfy an expanding set of international evaluative systems that were each designed in isolation and are now experienced together, at the same desks, on overlapping timetables.
An architecture built one piece at a time
No single body ever sat down to design the evaluative environment that a finance ministry in Nairobi, Accra, or Manila now operates inside. Sovereign credit ratings, International Monetary Fund debt sustainability analysis, Financial Action Task Force mutual evaluations, Basel capital and supervisory standards, the International Sustainability Standards Board’s disclosure requirements, ESG frameworks proliferating across investor and regulatory bodies, the Taskforce on Nature-related Financial Disclosures, and public financial management assessments each arrived on their own timetable, responding to their own crisis or constituency. Basel followed a banking failure. Debt sustainability analysis followed a debt crisis. Mutual evaluations followed a terrorism-financing scare. ISSB followed a decade of fragmented corporate sustainability reporting. Each has a coherent internal logic, and each, considered on its own, addresses something governments have genuine reason to take seriously.
There is a second, more structural reason why this burden concentrates so heavily on governments in the global south. Development finance has drifted, gradually and without much overt design, away from official and concessional support and toward private capital as the preferred mechanism for closing the financing gap between the global north and south. The shift is the product of many separate decisions taken across governments, markets, and international institutions. Whatever the motivations behind those decisions, the cumulative effect has been to disperse evaluation across an expanding range of actors rather than concentrate it within a relatively small number of official development partners. It is nonetheless consequential for the argument here. Official aid relationships carried their own conditionality, but that conditionality ran through a comparatively small number of bilateral and multilateral counterparts. Private capital brings no equivalent single counterpart. It brings credit rating agencies, ESG frameworks, index providers, and the disclosure architecture that now accompanies bond issuance, each operating independently and each addressed to investors rather than to any coordinating development institution. Modern investors themselves are now remarkably diverse. The growing importance of private capital has amplified the practical significance of this accumulation.
The literature on policy accumulation has been documenting a parallel dynamic inside domestic government for some time. The ACCUPOL research programme, tracking social and environmental policy across twenty-one OECD countries over forty-five years, found that policy outputs pile up steadily while implementation capacity does not keep pace, producing what the project’s own researchers term a responsiveness trap: policymakers are rewarded for adopting new rules and rarely rewarded for building the administrative capacity to carry them out (CORDIS, 2024). Davis (2010) makes a related argument at the international level, describing the growth of non-financial obligations imposed on states through global governance regimes as a form of obligation overload, distinct from and largely unaddressed by the legal architecture built to manage overloads of sovereign debt. Neither literature was written about ESG, or about Africa specifically. Both describe the same underlying mechanic that Dentons observed in miniature: legitimate obligations accumulate faster than the capacity to meet them, and no single actor in the system is responsible for managing the total.
Network research on regulatory overlap adds a further layer. Straughter and Carley (2021), studying the structure of the United States federal regulatory system, found that the burden a given agency imposes is a function of its position within a wider network of overlapping mandates rather than the stringency of any one rule it enforces. Agencies connected to many other highly connected agencies generate disproportionate burden regardless of what each individual regulation asks for. The same structural logic applies to a finance ministry or a central bank sitting at the intersection of sovereign credit assessment, IMF surveillance, Basel implementation, and ESG disclosure. The burden these institutions carry depends less on the demands of any single framework than on how many frameworks converge on the same office.
Although these three literatures emerged independently, and none was written with the other two in mind, they describe different manifestations of the same structural dynamic. ACCUPOL documents the accumulation of domestic policy obligations. Davis documents the accumulation of international legal obligations. Straughter and Carley demonstrate that burden is generated by the structure of overlapping networks rather than by any single node within them. Read together, the three suggest that administrative pressure on a government institution is not simply additive, in the sense of one framework’s demands stacked on top of another’s. It is produced by interaction: by the fact that the same finite set of officials, calendars, and reporting systems must absorb all of the demands at once, and that no framework is designed with that absorption problem in view.
An expanding evaluative architecture
The table below sets out the principal systems now converging on the same set of domestic institutions in a typical developing economy. Ministries of finance, central banks, debt management offices, and securities regulators recur across the fourth column with striking regularity, despite the fact that each system in the first column emerged from a distinct policy conversation and reports to a distinct constituency.
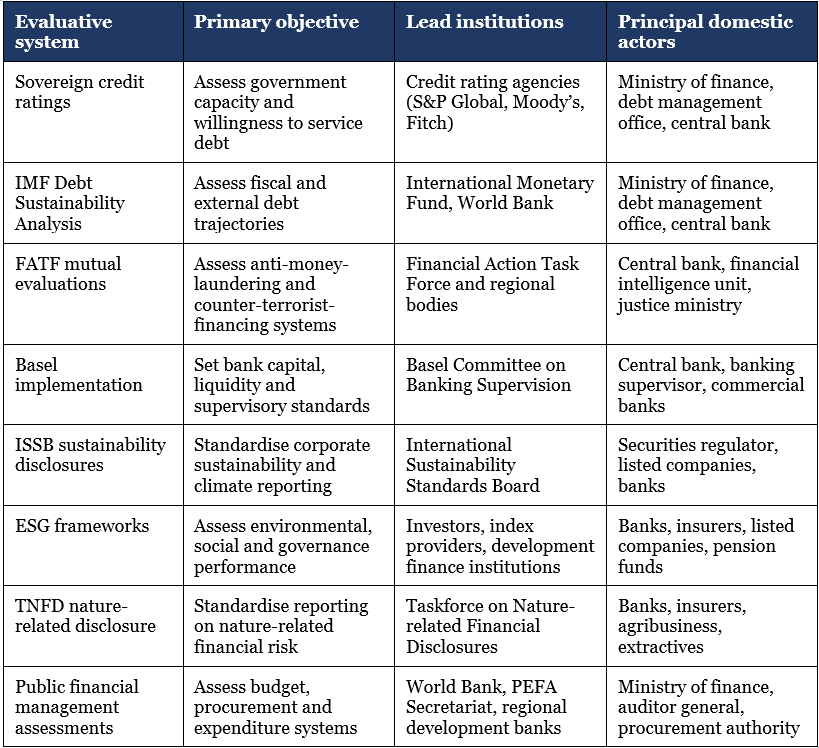
The table understates the overlap, since it treats each system as though it reported to a single domestic counterpart. In practice, a debt management office answering to IMF surveillance is frequently the same office whose bond issuance is scored by credit rating agencies, whose disclosures increasingly reference ISSB and TNFD frameworks, and whose banking counterparts must simultaneously satisfy Basel supervisors and FATF assessors. The systems were not built to share information or coordinate timing. They converge anyway, because they converge on the state.
Kenya as illustration
Kenya shows what this convergence looks like inside a single institutional environment. The Central Bank of Kenya issued guidance in 2021 requiring regulated banks and mortgage finance companies to embed climate-related risk into governance, risk management and disclosure practice, a reform the African Development Bank’s regional survey identifies as placing Kenya among the more advanced jurisdictions on the continent for climate-risk regulation (GCA, 2022; Central Bank of Kenya, 2021). The same survey notes that Kenyan market institutions have issued parallel ESG disclosure guidance, extending the reform beyond banking supervision into wider capital markets practice.
This sits on top of an older layer of evaluative engagement rather than replacing it. Kenya has, for decades, been a case study in the politics of converging on international banking standards for reasons of reputational signalling. Upadhyaya’s (2020) account of Kenyan Basel implementation situates the country’s adoption within an ambition to position Nairobi as a regional financial hub, a strategy that Jones (2020) identifies as one of the strongest drivers of standards convergence across her project’s cases: politicians seeking international capital treat compliance with international standards as a low-cost signal of sound regulation, precisely because investors and credit rating agencies use compliance as a shortcut for assessing a financial sector they cannot otherwise observe in detail. That institutional muscle for absorbing new international standards was already conditioned by decades of Basel engagement before climate risk and ESG disclosure were added to the workload, and the same supervisory staff and reporting cycles now carry all of it at once. The point of the illustration is not whether Kenya manages this convergence well or badly. It is that the convergence exists at all, inside a jurisdiction whose regulatory capacity is often held up as comparatively strong within the region.
The accumulation problem, considered on its own terms
Each framework in the table above has a plausible answer to the question of why it exists. None of them has a mandate to ask what happens when a finance ministry, a central bank and a securities regulator must satisfy all of them at once, using the same finite pool of trained staff, the same finance minister’s attention, and the same annual reporting calendar.
Barba (2026) offers a useful vocabulary for this problem, developed in an entirely different domain. Writing on research governance, Barba describes institutional friction as the cumulative and largely invisible cognitive cost generated when legitimate oversight mechanisms, none individually excessive, operate simultaneously on the same actors. The cost does not show up in any single framework’s compliance statistics, because no single framework is responsible for it. It shows up instead in fragmented attention, in the substitution of administratively visible activity for substantively difficult work, and in a widening gap between what institutions report and what they are actually able to absorb and act on. Knill, Steinebach, and Zink’s concept of policy triage describes the resulting behaviour at the level of the implementing organisation: when administrative capacity fails to expand alongside accumulating obligations, agencies do not fail uniformly, they ration attention, quietly prioritising the tasks that carry the most political or reputational exposure and deferring the rest (Zink, Knill, and Steinebach, 2025).
Applied to development finance, the implication is not that any of the frameworks listed above should be weakened. Sovereign credit assessment, debt sustainability surveillance, anti-money-laundering evaluation, prudential supervision, and climate disclosure each address a real and separate risk. The implication is that the capability required to satisfy all of them at once, coherently and on schedule, is itself a distinct institutional asset, and one that almost no evaluative system treats as its own concern. Individual frameworks evaluate governance. Collectively, they require something different: evaluative capability, the capacity to absorb, sequence and respond to multiple evaluative demands without any one of them being dropped. A ministry of finance that performs adequately against IMF debt sustainability criteria while simultaneously absorbing a FATF mutual evaluation, a Basel implementation timetable and a new ISSB disclosure requirement experiences these, in practice, as a single coordination challenge wearing four institutional faces. The frameworks generating that challenge have no shared mechanism for noticing it.
Development policy has traditionally invested in the things that are easiest to see: roads, ports, public financial management systems, debt management offices. It has devoted far less attention to the institutional capability required to work through an expanding architecture of international evaluation, even though that capability increasingly determines whether the investments in roads and ports can be financed at all.
Davis’s insolvency analogy is instructive here, even though it was developed for a different kind of overload. Sovereign debt overload has an entire legal architecture, however imperfect, built specifically to manage the interaction of competing claims on a state with limited capacity to meet them: restructuring frameworks, creditor coordination mechanisms, and doctrines for prioritising among obligations. Non-financial obligation overload, Davis argues, has no equivalent, because the bodies supervising each obligation deal with their own domain in isolation and have neither the mandate nor the practical means to weigh their demands against everyone else’s (Davis, 2010). The same absence characterises the evaluative architecture surrounding development finance. There is no body whose job is to ask whether the cumulative demands of sovereign credit assessment, multilateral surveillance, prudential standards and sustainability disclosure are proportionate to what a given finance ministry can actually deliver in a given year.
An open question
If access to international capital increasingly depends on satisfying an expanding array of evaluative systems, each legitimate and each partial, the question worth asking is no longer confined to how any single framework might be better designed or more sensitively applied to developing-country conditions. It is whether development policy should begin treating the capability to absorb, sequence, and act on evaluative demands collectively as an institutional asset in its own right, one that multilateral partners help build deliberately, rather than one that is simply assumed to exist and quietly eroded every time a new framework arrives at the same office door. The challenge for development policy may, in other words, be shifting from helping governments satisfy individual evaluative systems to helping them govern the growing architecture of evaluation itself.
References
Barba, S. (2026) ‘Science off the books: institutional friction and the invisible costs of research governance’, Science and Public Policy, 00, pp. 1–6.
Central Bank of Kenya (2021) Guidance Note on Climate-Related Risk Management. Nairobi: Central Bank of Kenya.
European Commission, CORDIS (2024) ‘Unlimited Growth? A Comparative Analysis of Causes and Consequences of Policy Accumulation (ACCUPOL)’, Periodic Reporting, Grant Agreement ID 788941. Available at: https://cordis.europa.eu/project/id/788941/reporting (Accessed: 25 July 2026).
Davis, K.E. (2010) Obligation Overload: Adjusting the Obligations of Fragile or Failed States. Unpublished working paper, New York University School of Law.
GCA (Global Center on Adaptation) / African Development Bank (2022) Climate Risk Regulation in Africa’s Financial Sector and Related Private Sector Initiatives. Rotterdam: Global Center on Adaptation.
Jones, E. (2020) ‘The Politics of Regulatory Convergence and Divergence’, in Jones, E. (ed.) The Political Economy of Bank Regulation in Developing Countries: Risk and Reputation. Oxford: Oxford University Press, pp. 65–82.
Muriithi, K. (2026) ‘Africa’s financial sector faces growing ESG divide as global capital outpaces domestic regulation’, African Sustainability Matters, 23 July.
Straughter, J. and Carley, K. (2021) ‘Towards a network theory of regulatory burden’, Applied Network Science, 6(70).
Upadhyaya, R. (2020) ‘Kenya: “Dubai” in the Savannah’, in Jones, E. (ed.) The Political Economy of Bank Regulation in Developing Countries: Risk and Reputation. Oxford: Oxford University Press.
Zink, D., Knill, C. and Steinebach, Y. (2025) ‘Bureaucratic overload and organizational policy triage: A comparative study of implementation agencies in five European countries’, Regulation & Governance, 19(3), pp. 637–655.